Sacramento, CA — Ten home insurance companies have sought $571 million in rate hikes under Insurance Commissioner Lara’s rules allowing insurers to raise rates based on black box climate models, yet those companies have committed to sell just 12,000 new home insurance policies. Commissioner Lara’s rules have failed to improve access to insurance for Californians, Consumer Watchdog said today.
At the same time, financial reporting shows home insurers in California and across the U.S. raked in record profits through the first half of the year, with Allstate as a standout.
Allstate is the latest insurer to seek a rate hike – $10 million – under the new rules. The company promises to sell 2,000 new home insurance policies, just a fraction of the 74,000 policyholders the insurer has dropped since 2023. All told, Californians would pay about $47 thousand in rate hikes for each new policy promised.
In return for using models Lara’s rules were supposed to increase access to home insurance, but massive loopholes have allowed insurance companies to raise rates without significantly expanding sales. Read more. Ten insurance companies, including seven of the eight largest in the state, have sought rate increases under the regulation, yet only five have committed to a small increase in sales. The other five are using black box models under the rule while making zero commitment to increase coverage.
Consumer Watchdog’s analysis is drawn from insurance companies’ rate filings at the Department of Insurance. A detailed tracking spreadsheet is available upon request.

Since the regulations were announced three years ago this month, enrollment on the FAIR plan has more than doubled – climbing from 320,581 to 675,229 individual policyholders by June 2026. Including another 320,000 homeowners with unregulated surplus lines coverage, approximately one million Californians have now been forced out of the standard insurance market and into FAIR or surplus carriers.
“Did California homeowners come out ahead on a deal that lets insurers raise rates without showing their math? The answer is a resounding no. Half a billion in rate hikes only coaxed insurers into promising a few thousand more policies. That doesn’t add up to better insurance coverage for California homeowners; far less Californians have standard home insurance now than when Lara started. As the FAIR Plan continues to grow Lara’s plan has failed to meaningfully improve insurance options in California,” said Carmen Balber, executive director of Consumer Watchdog. “Lawmakers and the next commissioner must do better – including a direct tie between wildfire mitigation and a home insurance guarantee – if we want to keep Californians insured.”

Insurance industry profits are soaring, giving the lie to industry claims that insurance regulation in California prevents them from making a profit, said Consumer Watchdog.
According to the latest numbers released by the National Association of Insurance Commissioners (NAIC) in August, 2024 insurance profitability across each line of insurance, broken down by state, shows that California homeowners insurance companies did better than the nation in 2024, and on average over the last two decades.
Direct return on net worth – a measure of profitability that includes insurers’ largest source of income, investments – for the homeowners line of insurance rose to 26.3% in California for 2024, compared to an average 23.9% nationwide. Over the past 20 years, California’s average return on net worth was 9.7%, compared to 6.4% nationwide.


A report (opens in new tab) issued by industry vendor Verisk and the American Property Casualty Insurance trade association this month reported soaring property casualty insurer profits in the first half of 2026. Net underwriting income – money left over after the company pays all claims and overhead and before investment income is calculated – was $31.7 billion for the first half of 2026.
Allstate’s 2nd quarter 2026 (opens in new tab)net income jumped to $3.2 Billion, 56% higher than last year. The insurer reported an adjusted net income return on equity of 44.2% over the past 12 months and Allstate’s property-liability underwriting income also soared, increasing nearly 57% to $2 billion. Policies in force grew 3.8% to 215.9 million.
2025 was also a banner year for property insurers nationwide that enjoyed $68.7 billion in underwriting income in 2025 and more than $111 billion in investment income, according to an analysis by Public Citizen and the Revolving Door Project of the NAIC annual report (opens in new tab).
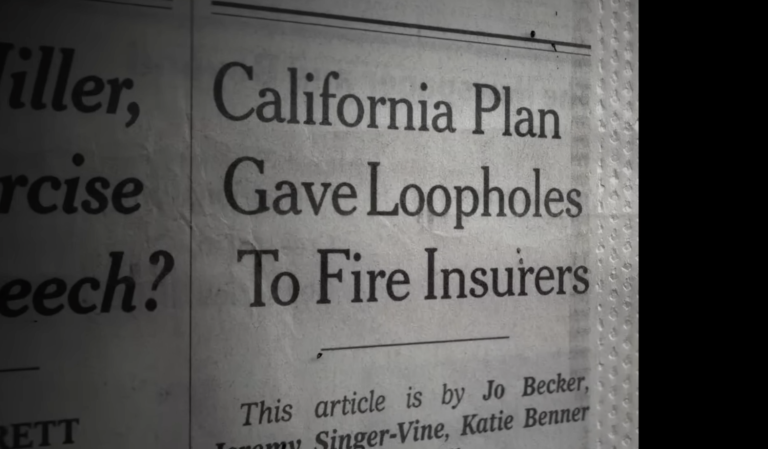
A New York Times front page investigation, “California Promised Insurance Relief But Delivered Loopholes,” explained how the regulations have huge loopholes that allow companies to raise rates without covering more people, despite their promise to do so. Read more.