Introduction
The Vanderbilt University Policy Accelerator for Political Economy and Regulation has issued a detailed report on the insurance crisis currently plaguing the United States. Authored by Brian Shearer, the Policy Accelerator’s Director of Competition and Regulatory Policy, “Regulating Insurance as a Public Utility” presents a compelling history of insurance regulation and proposes a new regulatory paradigm to address insurance overcharges. An accompanying policy brief, “How to Lower the Insurance ‘Tax’ by $150 Billion,” contains draft state and federal legislation to implement the proposal.[1]
The Vanderbilt proposal calls for the establishment of a federal and/or state minimum 80% “loss-ratio” regulatory standard, modeled on a similar component in the federal Affordable Care Act.[2] The proposal would require property-casualty insurance companies to spend at least 80 cents of every dollar they collect on claims and reinsurance expenses.[3] All other expenses would effectively be limited to 20 cents of the dollar. If an insurer spent less than 80 cents on claims and reinsurance, it would be required to automatically refund the difference after the insurer closes its books each year.[4] Insurance companies would be required to submit annual reports to a regulator with data supporting their compliance.[5] Regulators, law enforcement, and policyholders would be authorized to take legal action for failure to issue required refunds.[6]
This memo discusses how the proposal would work; how it compares to other state insurance regulatory systems; legal and practical vulnerabilities; whether it is compatible with California’s Proposition 103; and how establishment of a dual federal/state regulatory regime would interact with different regulatory regimes.
In summary: the Vanderbilt proposal is a timely and valuable analysis of the insurance marketplace in the United States. It concludes that insurance companies are massively overcharging their customers. That alone should trigger a re-evaluation of the current narrative concerning the insurance crisis, a narrative presently dictated largely by the industry. However, in its current form, the proposal raises significant legal and regulatory issues. These include redundancies and potential conflicts with existing state regulatory regimes (such as California’s) and disputes between state and federal regulators.
- How It Works
The insurance industry, regulators and actuaries frequently employ loss ratios to quantify financial and claims performance. Two commonly used loss ratios are (1) the direct loss ratio, which measures the proportion of premium income an insurer pays out for claims and (2) the net loss ratio, which calculates the percentage of premium dollars an insurer pays out in claims and claims adjustment expenses, after accounting for reinsurance premiums paid out and reinsurance reimbursements received.
The Vanderbilt proposal, by contrast, considers what insurers spent during a given period in the past to provide insurance coverage—outflows (not only claims payments but reinsurance premiums paid by the insurer)—as a percentage of inflows (money received from policyholders and payments from reinsurers under the reinsurance contract). Put another way, the proposed ratio measures an insurer’s historical expenditures for providing insurance coverage relative to revenue the insurer obtained from providing coverage.
Specifically, it requires insurance companies to satisfy a ratio under which claims payments (losses) and reinsurance premium payments the company makes on an annual basis equal at least 80% of the amount the company collects from policyholder premiums and payments from reinsurance companies. An insurer may use the remaining 20% of insurance-related revenue to cover expenses other than reinsurance, and profit.
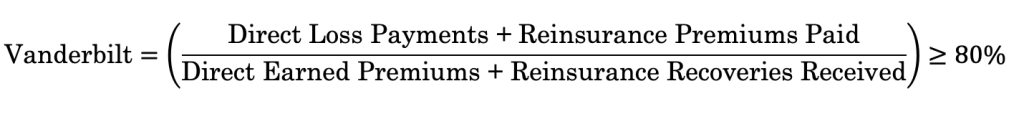
At the end of each “plan year,” insurance companies would file a report with the regulator containing the data from which each insurer’s ratio was computed.[7]
If an insurer spent less than 80% of its premium dollar on claims and/or reinsurance on an annual basis, the company would be required to automatically rebate the difference to policyholders.[8] If the insurer spends more than 20% of its premium dollar on expenses, it will have to cover those expenses out of its own resources.
Technically speaking, the formula proposed by Vanderbilt is not a “loss ratio.”[9] It is better described as a new metric to assess whether policyholders as a group have been receiving full value for the premiums they pay—a value ratio.
- How the Ratio Compares to Other State Regulatory Systems
The Vanderbilt ratio is a new and entirely different methodology for protecting policyholders against overcharges.
A. This New Form of Review is Retroactive, Not Prospective
To regulate insurance rates, most states have adopted a legal standard devised by the insurance industry and adopted by the National Association of Insurance Commissioners[10] in the 1940s. It prohibits rates that are “excessive, inadequate or unfairly discriminatory.”[11] The form of regulation can vary widely, however. Some states require companies to apply for rate increases that are reviewed and must be approved before they take effect (“prior approval”); others allow companies to “file and use” the rates, permitting a regulator to object to a rate after it takes effect. Still others rely on “open competition,” under which rates are “set” by the “free market.” Under these regulatory systems, there is one constant: insurance companies use various methods to project the rates they will need in the future.
The Vanderbilt ratio is not intended to replace state regulation of prospective rates. Rather, the ratio review it proposes would occur after the rates have been charged. It is a retrospective review. At the end of each “plan year,” insurance companies would file reports with the regulator demonstrating compliance. In effect, the proposed formula determines whether the previously charged rate turned out to be excessive in practice. Put another way, the Vanderbilt ratio measures whether policyholders ultimately received sufficient insurance protection in exchange for the premiums they paid.
B. Important Elements of a Rate are Not Defined or Not Directly Regulated by the Vanderbilt Ratio
Cash Outflows. The ratio recognizes only two specific cash outflows: losses (i.e. claims payments by the insurance company to policyholders) and premiums paid by the insurance company to buy reinsurance. (Reinsurance is a product that insurance companies purchase to backstop future losses and enable companies to sell more insurance by shifting some of the risk.)
Insurance companies would be able to use premium income to pay for other cash outflows to the extent they do not exceed 20% of the premium dollar. The proposal thus effectively caps the amount of premium that may be used to finance cash outflows—other than losses and reinsurance premiums—at 20%. If cash outflows exceed the 20% cap, insurance companies would have to cover the excess from their profits.
The proposal does not define the numerator: “total losses” (or as we described above, “direct loss payments”). How those terms are defined makes a critical difference in how the acceptable level of losses is calculated. For example, insurance companies spend significant portions of the premium dollar on expenses related to claims, in a category known as “loss adjustment expenses.” If insurance companies were to treat loss-adjustment expenses as part of “losses” for purposes of the ratio, insurers would have an incentive to move ordinary overhead, vendor charges, legal expenses, claims administration, and data costs into the “loss payments” numerator of the formula. This would enable the insurer to greatly inflate its losses.
An insurance company’s transactions with claims handling affiliates are another way to arbitrarily inflate losses. An insurance company that owns a claims adjusting company could pay the affiliate an above-market price for its claims services, effectively transferring profits to the affiliate.
Finally, the ratio’s focus on the pass through of “reinsurance” expenses is itself a significant vulnerability. Insurance companies often “buy” reinsurance from affiliates, a well-documented conflict of interest that would allow an insurer to inflate its payouts and manipulate the ratio. Additionally, the reinsurance market is global and unregulated. That market is notoriously unstable; unexpected losses have quickly translated to wild gyrations and exorbitant increases in reinsurance premiums. For that reason, as discussed below, California regulators have, until recently, long excluded consideration of reinsurance costs in rates.
The Vanderbilt ratio does not place mathematical limitations upon other insurance expenses that can be manipulated to influence the ratio:
- advertising
- marketing
- agent commissions
- management fees
- lobbying
- trade association dues
- executive compensation
- salaries
- dividends
- stock buybacks
- rate case expenses
- general overhead
- investor relations
- corporate entertainment
- private jets
The ratio itself does not directly regulate these expenses. Nor does the ratio itself require insurers to justify these expenses or place limits on them. Rather the proposal requires insurers to annually disclose these expenditures and calls for regulations that would limit insurance companies from using corporate funds for certain expenses, explicitly banning only two categories of expenses: private jets and stock buybacks.[12] Otherwise, it urges the regulator to aim for “cost efficiency so that as little premium revenue is spent on selling expenses, overhead, and other costs as possible,” including “unreasonably high executive compensation,”[13] general statements that would require further regulations to implement. Under traditional regulatory environments, some states control these variables more precisely. California regulations, for example, do so, by restricting or barring their pass through.[14]
Loss Development, Premium Trend, Loss Trend; Catastrophe Adjustments; Credibility. Insurers use these actuarial tools to measure and predict their future financial needs; in a traditional rate-setting environment, these measures should also be reviewed by the regulator. The value ratio omits them almost entirely because they are irrelevant to its retrospective review: rather than asking what future losses are expected to be, the ratio asks what the losses actually were.[15]
Investment Income. Insurance companies earn substantial investment returns when they invest policyholder premiums—investment income can be so significant that an insurer can afford to pay out more in dollars than it receives in premium—and still be financially healthy. The Vanderbilt ratio itself does not directly address investment income. But the proposal is based upon the economic premise that insurers require smaller underwriting margins precisely because the company receives investment income. By contrast, California’s insurance law explicitly requires that insurers include their investment income when proposing future rates.[16]
Profits. The Vanderbilt formula does not regulate profits directly; profits must come from the remaining 20% of the premium dollars collected by the insurance company. The Vanderbilt study explicitly states that insurers should be expected to tolerate underwriting losses since they can be offset by investment income. And it appears to leave underwriting profit to the state regulator’s review of rate requests.[17]
C. Application to Multiple Lines of Insurance
The Vanderbilt proposal cites the Affordable Care Act as a model for the proposed ratio. However, health insurance is not analogous.
Property casualty insurance includes at least 28 different lines of business (such as Homeowners, Private Passenger Auto and Commercial Multi-Peril).[18] There is a very wide degree of variability in losses between many lines of business, not to mention across states with varying degrees of exposure to catastrophic losses (think wildfires in California, tornadoes in Kansas, and hurricanes in Florida). Property-casualty insurance is, historically, more volatile than health. This is especially a problem in light of the ratio’s explicit inclusion of reinsurance premiums, which are notoriously unstable, as noted above.
Moreover, unlike health insurance, some lines of property/casualty insurance are extremely “long tailed,” meaning that the ultimate amount of claims payments will not be known for many years. As of any given evaluation date, only a portion of a P&C insurer’s claims for any given year will have been paid. It would not make sense to base an insurer’s ratio on the paid loss amount alone: for example, if an insurer receives $1 million in premiums during a calendar year, but has only paid out $500,000 during that year, it will show a 50% paid loss ratio and would be liable for refunds totaling 30% of premiums, or $300,000, using the minimum loss ratio of 80%. But in the case of a long-tailed line, the ultimate amount of claims payments for that year will likely be higher—potentially much higher—than $500,000 once all claims are paid in full.
This is particularly true for natural catastrophes like wildfire or earthquake and the lines of business they impact. In one such line, homeowners’ insurance, the tails for claims can extend far beyond the year of the loss. For example, in the case of accident years 2017 and 2018, which saw significant losses due to wildfires in California, many claims were not fully settled for years. Compounding this is the impact of subrogation payments, where a third party (in this case, a utility company) is found liable for some portion of catastrophic losses and is required to reimburse insurers for what they’ve already paid out to policyholders. Subrogation payments by utilities for the 2017 and 2018 fires did not get booked into insurers’ financial statements until 2020 and 2021.[19] Under the Vanderbilt proposal, those payments would not be reflected in refunds until many years after the premiums were paid, altering the calculation of the annual ratio, and potentially rewarding recent policyholders, not the ones who paid premiums in the years when catastrophe claims were paid.
The proposal’s response to the problem created by applying the “plan year” benchmark to long-tailed lines is a three-year averaging rule.[20] It would smooth year-to-year volatility, but it does not address the large variations in claims development by line. In any given year (especially the most recent), the claims record will be incomplete depending on the length of the tail; averaging the ratio over several years of incomplete claims will not redress this flaw in the proposal for the most severe disasters.
The proposal provides a single exception to the across-the-board 80% ratio: it allows an adjustment to the ratio for a particular line of insurance—but only if the 80% requirement would create an “imminent risk of insolvency”—not because a line’s losses are volatile or long-tailed.[21] (Nor can an adjustment be made for a single company according to the model bills, even though the Article refers to a “specific insurer…at risk of insolvency.”)[22] Administering this “financial emergency” exception raises serious legal and practical vulnerabilities, discussed below.
Finally, the example above, describing $500,000 in paid claims under a long-tail policy, illustrates the consequences of the Vanderbilt proposal’s failure to define “losses.” An insurer forced to rebate $300,000 is not necessarily repaying a true overcharge—it may be refunding money it will need, in full, to subsequently pay the outstanding claims. That creates a solvency risk for an insurance company.
Interpreting “losses” to include estimates of the unpaid portion of claims (known as “incurred” losses) is how insurance companies commonly determine rates. They calculate and set aside the necessary funds in the form of “reserves.” But that actuarial approach creates a serious risk for policyholders under the Vanderbilt proposal: it would encourage insurance companies to artificially inflate their projected “losses” in order to escape the ratio’s refund requirement. An insurer with a 50% paid loss ratio could decide to engineer its reserves so that the ultimate loss ratio reaches 80%, not because insurance company executives and actuaries actually believe that losses will be that high, but merely to ensure that their loss ratio on paper is above the 80% threshold so they don’t have to refund any premiums.
Even in a state like California, where a thorough review of proposed rates is mandated by law, nothing in the rating law requires an insurer to alter the actual amount that the company holds in reserve—which is the same amount that the insurer will rely upon when it applies the ratio. In a rate case, a successful challenge to how the insurer turned old claims into a prediction of future losses, only changes the rate the Commissioner approves going forward. The company cannot be forced to go back and change the reserve number sitting on its books.[23]
For these reasons, the application of a one-size-fits-all minimum ratio is not appropriate for volatile and long-tailed lines of P&C insurance. The Vanderbilt proposal acknowledges as much, particularly for “less stable insurance markets.”[24] Nevertheless, the ratio would apply to earthquake, fire, and homeowners—among the most unstable markets in the current crisis.[25]
III. Legal and Practical Vulnerabilities
Elements of the Vanderbilt proposal are highly vulnerable to legal challenges.
A. Constitutional Issues
Insurance companies routinely challenge the constitutionality of reforms on the grounds that the reforms deprive them of due process, constitute a “taking” of their property without just compensation, or interfere with their First Amendment rights.
The “takings” argument was a centerpiece of the insurance industry’s frontal attack on California Proposition 103 after it passed. The insurers insisted that the 20% across the board rollback in premiums was confiscatory and denied insurers their right to a hearing on its financial impact. Proposition 103 contained an exemption from the rollback for insurance companies that were “substantially threatened with insolvency.” In upholding Proposition 103, the California Supreme Court invalidated that standard as unconstitutional, because it did not afford insurers the opportunity to obtain relief from rates that they claimed were confiscatory.[26] However, it found that Proposition 103’s general rate standard prohibiting excessive and inadequate rates provides a valid constitutional standard for rate adjustment because it requires rates within that “fair and reasonable” range and prohibits approval or maintenance of confiscatory rates under the inadequate standard. Under that standard, insurers were ultimately required to refund $1.2 billion.
Just as they challenged Proposition 103’s reforms in court, insurers are certain to contest the Vanderbilt formula.
The fixed nature of the Vanderbilt ratio will draw a generic constitutional challenge by insurance companies claiming it deprives them of a “fair return” because it does not sufficiently recognize how each company operates. Complicating the legal analysis is the “long-tailed” nature of claims in certain lines, as discussed above: a ratio computed before long-tail claims mature can compel a refund on losses that subsequently prove higher, which insurers would invoke as a factual predicate for a claim of unconstitutional confiscation.
Additionally, the proposal imposes serious constraints on the ability of an insurance company to refuse to renew policies or to withdraw from the state.[27] These are important protections, but without doubt would draw “due process” legal challenges from the industry.
But the refund requirement is likely to draw a more serious constitutional challenge. If an insurer did not spend the full 80%—say, the company only paid out 67 cents per dollar—it would be required to refund 13 cents per dollar. (The proposal requires the insurer to pay interest from the date when the refund was due; a company that keeps the overcharge through the plan year but issues a refund on time would owe nothing for its use of the policyholder’s money.) Insurers will argue that the refunds nevertheless deprive them of a fair return. Each insurance company will be entitled to a full hearing on that claim.
The Vanderbilt ratio focusses on insurers that turn out to have overcharged their customers; if actual losses are substantially lower than expected, consumers are to receive rebates. But what happens if an insurance company has paid out more than 80 cents of the dollar for claims and reinsurance—say as a result of a catastrophic wildfire? Under the Vanderbilt proposal, if payouts are higher than expected, the insurance company is responsible for the shortfall. This is a risk that insurers presently bear, but in the context of the bill’s refund requirements, will no doubt provoke a legal challenge by insurers.
As noted above, the Vanderbilt proposal contains a safety valve intended to address situations in which insurers experience financial distress: it authorizes a regulator to adjust the 80% ratio requirement if imposing it would “create imminent risk of insolvency.” However, that standard is quite similar to the “substantially threatened with insolvency” provision within Proposition 103 that was invalidated by the California Supreme Court in Calfarm.
It is likely that a majority of insurers—across the more than 1,400 state/line combinations—would claim that they are at an “imminent risk of insolvency” if held to the 80% ratio standard, and request relief. This would result in a high degree of “exceptions” to the 80% rule, or at the very least, a morass of insurer objections each year. While application of the ratio in ordinary circumstances is automatic, application of the emergency escape clause requires active government intervention. Even if all those exception requests are ultimately rejected, insurers can appeal such denials to the courts.
Moreover, the Vanderbilt proposal appears to contemplate that the insolvency adjustment to the ratio would be applied to all insurance companies in the market, or at least to all companies selling a particular line of insurance. Financially healthy insurers that required no financial relief would nevertheless receive a windfall, defeating the purpose of the ratio. There is also a timing mismatch: because the ratio applies to the prior plan year, a company that overcharged in the prior year but that has run into financial trouble in the current year would be reducing or eliminating refunds owed to previous customers in order to be able to service current customers.
The proposal could be amended to address these inconsistencies by requiring company-by-company relief and allowing currently distressed companies to postpone their refund obligations. But these procedures would need to be supported by extensive and complex regulations setting objective standards to determine which companies are entitled to relief, and when and how the postponed refunds would be paid. As a legal matter, the rollover of refund obligations should not impact a company’s rates in the future—but as a practical matter could do so.
B. Statutory Refund Issues
Many states do not permit refunds under a court-created doctrine known as the “rule against retroactive rates.” Insurers would likely argue that mandatory rebates constitute prohibited retroactive ratemaking because premiums would have been approved, charged, and earned before the rebate obligation arose. As noted below, California courts have barred both the insurance commissioner and the courts from ordering refunds when insurance companies overcharge consumers in violation of Prop 103, based on that rule—even though the language of Proposition 103 does not support its application.
C. Practical Issues
Although the proposal features a simple mathematical ratio, a great deal of further regulatory work would be needed to define terms and close loopholes, as discussed above. Just as drafting can minimize some of the significant legal vulnerabilities noted above, the careful promulgation of accompanying regulations may be able to resolve many of the issues.
But that raises two serious and related concerns. First, like most regulatory paradigms, the Vanderbilt proposal imposes enormous obligations on a regulator—but it does not call for institutional mechanisms of transparency and accountability that are necessary to prevent the industry from corrupting the process through regulatory capture. California addressed this danger by requiring full transparency in regulatory proceedings,[28] applying the protections of the Administrative Procedures Act,[29] and giving citizens an independent right to monitor and intervene in regulatory matters and be compensated for their efforts.[30]
Second, it is unclear whether those states that already regulate insurance rates would adopt an entirely new and separate framework for the retroactive “true-up” process contemplated by the Vanderbilt proposal. The answer to that question depends on the nature of the regulatory regime, if any, in place in each state. States with no meaningful regulation presently could choose to adopt the Vanderbilt methodology as an alternative to prospective, prior approval rate regulation. But those states will still need to create a significant regulatory apparatus to make the ratio work as proposed by Vanderbilt, and to address legal vulnerabilities.
For California, which arguably has the strongest regulatory regime of any state in the nation, a different assessment is necessary.
IV. The Ratio and Proposition 103
In 1988, Californians approved a ballot initiative that massively restructured the state’s insurance laws. Proposition 103 replaced the “free market” system enacted in 1947, under which there was no regulation of insurance rates and practices; the state’s antitrust, civil rights and consumer protection laws did not apply; and there was no transparency, no accountability or public participation.[31]
Proposition 103’s main reforms—the prior approval process, including public scrutiny and accountability, and how rates are set—have been subjected to frequent litigation by insurance companies. Until 2025, the regulations governing the Commissioner’s responsibility under Proposition 103 were for the most part unchanged since they were first promulgated.
Ratemaking formulas set forth in those regulations identify and preclude excessive rates: they specify the maximum and minimum rates an insurance company may charge (corresponding to the statutory “excessive” and “inadequate” standards). These detailed formulas include provisions for profits, expenses (including payments to affiliates)[32], investment income, ancillary income, projected losses, and costs associated with defense and cost containment of claims. The regulations further define each of these components by specifying data sources and additional formulas for how to calculate them.[33]
These are all components of the Prop. 103 ratemaking process and each is reviewed separately to fine tune the calculation of an acceptable prospective rate in a more precise and comprehensive way than the Vanderbilt ratio. Elements of the Vanderbilt proposal are therefore redundant of the existing Proposition 103 regulatory formula.
Similarly, the Vanderbilt proposal would require the California Insurance Commissioner to issue alternative regulatory definitions and formulas for purposes of calculating the applicable ratio and corresponding refunds. Since the passage of Proposition 103, insurance companies operating in California complain bitterly about having to comply with its regulatory requirements. Were the ratio adopted in California, they are likely to pit the two methodologies against each other, arguing that the Vanderbilt proposal will impose additional costs, and that they conflict.
The latter point is the greater concern. Applying two differing regulatory regimes to the same industry in the same state would create direct conflicts with existing state regulations.
An obvious example is built right into the Vanderbilt ratio. It explicitly allows insurance companies to include every dollar of reinsurance payments they make, without limitation or qualification, in each of 28 lines of insurance.[34] By contrast, until recently California regulations did not permit insurance companies to pass through the cost of reinsurance to policyholders, with limited exceptions for earthquake and medical malpractice lines, for precisely the reasons noted above: the reinsurance market is global, unregulated, notoriously unstable and riddled with conflicts of interest that enable price gouging.
In response to one of the insurance industry’s demands, California Insurance Commissioner Ricardo Lara issued a regulation in 2024 authorizing insurance companies to treat a portion of their reinsurance costs for specified catastrophe perils as expenses under Proposition 103 and pass them through to policyholders.[35] The new rule is expected to lead to massive increases in Californians’ insurance premiums.[36] But the regulation contains some putative limitations: a requirement of good faith, arm’s-length dealing and fair market valuations; disallowance of reinsurance between affiliated entities; for catastrophe risks in property lines, a requirement that insurers use a standardized benchmark rather than their actual reinsurance cost; and agreement to some modest commitments to resumption of sale of insurance in certain neighborhoods across the state. Thus the Vanderbilt proposal directly conflicts with current California regulations.
Moreover, Proposition 103 already contains within it the two key protections that the Vanderbilt ratio is intended to provide to consumers.
First, Proposition 103 grants the Commissioner the power to retroactively review whether existing rates are proper. As enacted, Proposition 103 bars excessive rates from “remaining in effect.”[37] The Commissioner has the power to order insurance companies to submit new, revised rate applications if it is determined that the previously approved rates have become excessive (or inadequate, or unfairly discriminatory, or otherwise illegal).[38] However, a 2021 decision by an appellate court in California concluded that the Insurance Commissioner does not have the authority to require an insurance company to pay refunds for “in effect” rates that became excessive.[39]
Second, like the Vanderbilt proposal, Proposition 103 explicitly creates a private right of action for consumers to seek refunds if they have been charged rates that were lawful when they were approved but later became excessive.[40]Unfortunately, there is a split among California’s intermediate appeals courts as to whether civil lawsuits can be brought against rates that the Commissioner has previously approved.[41]
According to the most recent rulings,[42] neither the courts nor the Commissioner can order an insurance company to pay refunds for overcharges. (This would be a major legal hurdle for the Vanderbilt proposal, as noted above.)
In summary, the Vanderbilt proposal advances a different methodology for protecting the public against overcharges, but one that is operationally redundant to—and would precipitate conflicts with—the requirements of Proposition 103.
V. A Federal Loss Ratio Requirement Would Create Statutory and Administrative Conflicts
The Vanderbilt proposal, if adopted at the federal level, would effect a major change in federal policy that implicates the McCarran-Ferguson Act, which has allocated authority over insurance companies between the federal government and the states since 1945.
A. Federal Regulation of Insurance Could Preempt State Regulation and Apply the Federal Antitrust Laws to the Insurance Industry
The McCarran-Ferguson Act states that “[t]he business of insurance, and every person engaged therein, shall be subject to the laws of the several States which relate to the regulation or taxation of such business.”[43] It continues, “No Act of Congress shall be construed to invalidate, impair, or supersede any law enacted by any State for the purpose of regulating the business of insurance, or which imposes a fee or tax upon such business, unless such Act specifically relates to the business of insurance….” (emphasis added).[44]
Vanderbilt’s proposed federal legislation “specifically relates to the business of insurance,” and therefore it would override state insurance laws. The Vanderbilt reports anticipates that Congress would both enact the ratio while at the same time preserving traditional state regulation of insurance companies, establishing a dual state/federal regulatory system: states would continue to regulate insurance companies (or not) as they do now, and would also adopt the Vanderbilt proposal, while the federal government would administer a loss ratio test on a retroactive basis, i.e., after state rates are approved.[45] However, such an arrangement would require Congress to expressly bifurcate authority in that manner. Absent an explicit “savings clause”—not present in the model federal legislation—state regulation would potentially be preempted.[46]
Whether and to what extent Congress would legislate to protect state insurance laws is a crucial practical consideration here. Insurance companies enjoy conditional immunity from the federal antitrust laws under the McCarran-Ferguson Act to the extent that state laws “regulate” insurance; indeed, that was the motivating force behind its passage in 1945. The application of McCarran’s constraints to the proposed hybrid federal/state regulatory system would create an opportunity for the insurance lobby to advocate for restrictions on state laws that diminish the power of state regulators to hold insurers accountable. A threshold question is whether Congress would choose to maintain the industry’s exemption from the antitrust laws even though states were no longer solely regulating the industry.
Indeed, it’s conceivable that, in light of the current political climate, insurance companies might decide to forfeit their exemption from federal antitrust laws altogether in exchange for exclusive federal regulation, given the reigning pro-deregulation stance of the major political parties.
What insurance companies are highly unlikely to agree to is what they would consider the worst of both worlds: retroactive federal review on top of 50-state rate regulation.
For consumers, the federal government’s new role in regulating the insurance industry would raise significant concerns, especially now that under a recent U.S. Supreme Court decision, the President would exercise complete political control over the federal agency put in charge of regulating the industry.[47]
B. As a Practical Matter, Dual Federal/State Regulation Would Be Difficult if Not Unworkable
The Vanderbilt proposal assumes that states will continue to exercise primary responsibility for the regulation of prospective rates (to the extent that a state does so presently) as they have since 1945. It envisions that states would enact the value ratio – and a host of regulations in connection with it – as a retrospective review of rates that were in effect in each state for the previous year. However, it also accords the federal government responsibility for implementing a parallel federal value ratio. As drafted, this dual state/federal loss ratio approach is likely to generate considerable conflicts, and create confusion, if not disarray.
Joint state and federal regulation will be complicated to administer. State regulation of rates varies widely, as noted above. It relies on actuarial and accounting rules that reflect a different paradigm of regulation than an after the fact application of the ratio as a cross check. While states have decades of experience in the regulation of property-casualty insurance companies, the federal government has none. The proposal requires a federal regulatory agency—the Federal Insurance Office, presently a modest monitoring program within the U.S. Treasury—to coordinate with fifty state regulators in administering the law.[48] To do so, it would have to replicate at least some of the staff expertise, information gathering, and monitoring functions of state regulators, a major expansion of its jurisdiction that would require additional legislative authorization.[49]
Moreover, dual regulation invites politics into the process, by potentially pitting state officials against appointed counterparts at the federal level, who under present court rulings serve at the pleasure of the President.[50] For example, a federal order to pay refunds implicitly reflects on the quality of a state’s prospective regulation and could be construed as evidence of a state’s failure to approve a reasonable rate (or reject an unreasonable rate) in the first place.
An overarching source of conflicts would be instances when rate inadequacy creates imminent financial problems for an insurance company. As a general matter, solvency has always been a concern of state regulators, and they are far better equipped to anticipate and manage such situations quickly, whereas the minimum ratio approach is a retrospective review that is not conducted for months after the close of the year. A company could fail the ratio test and be required to pay refunds for a prior year’s overcharges, at the same time that it experiences unexpected losses that endanger its financial stability in the current year, precluding the payment of refunds.
The Vanderbilt proposal generates further complexity in the context of solvency issues. Under the Vanderbilt federal model law, the only power a state regulator has over the ratio is to increase it above 80%.[51] However, under the state model law, the only thing the state insurance commissioner may do to the number is lower it.[52] Consider the following scenario, assuming both proposed laws are in effect: A state regulator determines that applying an 80 percent requirement to homeowners insurance in her state will drive companies into failure. They lower the state requirement to, say, 70 percent. That state action does not alter what the insurance company owes that state’s policyholders under proposed federal legislation: The federal 80 percent requirement still applies, the federal rebate is still owed, and policyholders can still sue to collect it. Absent timely resolution of the conflict, the state regulator’s rescue could be nullified.
The scope of authority over imminent risk of insolvency also differs between the state and federal legislation. Under the federal model law, the Director may adjust the percentage for a whole state, for a whole type of insurance, or for a public insurance plan.[53] The state commissioner may adjust it for a particular line of insurance.[54] (Neither may adjust it for one company.)
Similar differences are apparent in the kinds of remedies available for violations of the ratio. The two model bills share four remedies: the unpaid rebate itself, interest on it, punitive damages, and costs and attorney’s fees. The state plan adds four remedies the federal scheme does not have: damages, remediation, restitution, and the proceeds of unjust enrichment.[55] For the identical failure to pay the identical rebate, therefore, a company’s exposure is materially different depending on which law is applied to it. Insurers would be better off lobbying the federal government to act first to preempt the broader remedial powers wielded by the state regulator.
Internal inconsistencies aside, conflicting goals and decision making between the state and federal governments would be a constant feature of the dual regulatory framework. Insurers would be highly incentivized to attempt to exploit these conflicts for their own advantage.
Conclusion
Insurance presents the quintessential affordability dilemma, as the Vanderbilt study demonstrates. Required by law, contract and prudential business practices, insurance is a product that everyone needs but no one hopes to use. Few understand it. When the insurance industry initiates an insurance crisis by boosting premiums and withdrawing from markets, it typically has the upper hand. In many states, the industry operates in an informational and governmental vacuum in which its actions are not subject to the scrutiny of an independent, pro-consumer regulator, nor readily accessible to the news media and the public. Armed with unlimited resources and a legion of lobbyists and experts, insurers all too often control the narrative in state capitols. The silence of elected officials in the face of the latest crisis has been deafening.
The Vanderbilt study is a timely and valuable analysis of the insurance marketplace in the United States. Applying its ratio, it concludes that insurance companies are massively overcharging their customers. That alone should trigger a re-evaluation of the current narrative concerning the insurance crisis, presently dictated largely by the industry.
In any case, there are significant legal and policy questions about the application of the proposed ratio. Moreover, though the ratio itself is simple and straightforward, implementing it as a regulatory standard would not be. It would require many states to significantly expand their regulatory oversight, and in some states, such as California, generate contradictions and inconsistencies with existing law. Potential state and federal conflicts complicate the joint approach suggested by the study. For California, the key protections that the ratio seeks to provide are already part of existing law and need only to be respected by the courts and enforced by the insurance commissioner.
[1] Both documents were published in April 2026 and are available at https://www.vanderbilt.edu/vanderbilt-policy-accelerator/insurance/. Regulating Insurance as a Public Utility is cited below as the “Article”; How to Lower the Insurance “Tax” by $150 Billion is cited as the “Policy Brief.” The two model bills appear as Appendix A (federal) and Appendix B (state) to the Policy Brief.
[2] Article pp. 75–76. The Affordable Care Act’s medical loss ratio requirement is codified at 42 U.S.C. § 300gg-18(b).
[3] Federal Model Bill § 313(u)(1)(A); State Model Bill § 4(b)(1)(A).
[4] Federal Model Bill § 313(u)(1)(A)–(B); State Model Bill § 4(b)(1)(A)–(B).
[5] Federal Model Bill § 313(t)(2)–(3); State Model Bill § 4(a)(1)–(2).
[6] Federal Model Bill § 313(u)(4)(B)–(C); State Model Bill § 6(b)–(c).
[7] Federal Model Bill § 313(t)(2); State Model Bill § 4(a)(1).
[8] Federal Model Bill § 313(u)(1)(A)–(B)(i); State Model Bill § 4(b)(1)(A)–(B)(i).
[9] A more technical explanation: a traditional loss ratio has all loss elements in the numerator and all premium elements in the denominator. The Vanderbilt formula presents a different methodology: it has direct losses + reinsurance premiums in the numerator, and direct premium collected + reinsurance loss recoveries in the denominator.
[10] The NAIC is a non-profit organization funded primarily by the insurance industry.
[11] See, e.g., California Insurance Code § 1861.05(a); 20th Century Ins. Co. v. Garamendi (1994) 8 Cal.4th 216, 251–253.
[12] Federal Model Bill § 313(u)(3); State Model Bill § 4(b)(3).
[13] Federal Model Bill § 313(u)(2), (u)(3)(C); State Model Bill § 4(b)(1)(C), (3)(C).
[14] See Cal. Code Regs., tit. 10, § 2644.10 (“Excluded Expenses”), which excludes from the ratemaking calculation political contributions and lobbying (subd. (a)); executive compensation exceeding a reasonable amount (subd. (b)); bad faith judgments and associated defense and cost containment expenses (subd. (c)); costs attendant to the unsuccessful defense of discrimination claims (subd. (d)); fines and penalties (subd. (e)); institutional advertising expenses (subd. (f)); and “[a]ll payments to affiliates, to the extent that such payments exceed the fair market rate” (subd. (g)).
[15] See Cal. Code Regs., tit. 10, §§ 2644.4 (projected losses), 2644.5 (catastrophe adjustment), 2644.6 (loss development), 2644.7 (loss and premium trend), and 2644.23 (credibility adjustment).
[16] Cal. Ins. Code § 1861.05(a); 20th Century Ins. Co. v. Garamendi (1994) 8 Cal.4th 216, 251; Cal. Code Regs., tit. 10, §§ 2644.20.
[17] Article pp. 71–72; but note that the model state law takes a different approach: it requires an annual rebate of all underwriting profit. (State Model Bill § 4(b)(2)).
[18] Federal Model Bill § 313(t)(1); State Model Bill § 3.
[19] See Consumer Watchdog comments to California Earthquake Authority SB 254 inquiry, Dec. 12, 2025 (https://consumerwatchdog.org/wp-content/uploads/2025/12/SB-254-Consumer-Watchdog-12-12-25.pdf).
[20] Federal Model Bill § 313(u)(1)(B)(ii); State Model Bill § 4(b)(1)(B)(ii).
[21] Federal Model Bill § 313(u)(1)(A); State Model Bill § 4(b)(1)(A). Neither provision permits an adjustment on account of volatility or the length of a line’s claims tail.
[22] Article p. 72.
[23] California law addresses the adequacy of loss reserves, but only for solvency purposes—there is no counterpart directed at reserves that are excessive—and not in the context of rate review. (See Ins. Code § 923.5; § 11556; § 11557; § 11558; and § 923.6.) There is no counterpart directed at reserves that are excessive. What is reviewable in a rate proceeding is the insurer’s selection of a loss development basis. (Cal. Code Regs., tit. 10, § 2644.6). A successful challenge changes the rate approved going forward; it does not alter the insurer’s booked reserve.
[24] Article p. 76.
[25] Federal Model Bill § 313(t)(1); State Model Bill § 3.
[26] Calfarm Ins. Co. v. Deukmejian (1989) 48 Cal.3d 805, 818–823.
[27] State Model Bill § 5.
[28] Cal. Ins. Code § 1861.07.
[29] Cal. Ins. Code § 1861.08.
[30] Cal. Ins. Code § 1861.10.
[31] King v. Meese (1987) 43 Cal.3d 1217, 1240; 20th Century Ins. Co. v. Garamendi (1994) 8 Cal.4th 216, 240.
[32] Note that “excessive” payments to affiliates (payments exceeding fair market value for services provided) are one of the excluded expenses under California regulations. (Cal. Code Regs., tit. 10, § 2644.10.)
[33] Cal. Code Regs., tit. 10, §§ 2641.1 et seq.
[34] Federal Model Bill § 313(u)(1)(A) and § 313(t)(1); State Model Bill §§ 3, 4(b)(1)(A).
[35] Cal. Code Regs., tit. 10, §§ 2644.25.1, 2644.25.3 and 2644.27(f)(11).
[36] Consumer Watchdog, December 30, 2024 (https://consumerwatchdog.org/insurance/lara-reinsurance-regulation-to-pump-up-homeowners-rates-by-40-without-guarantees-of-new-wildfire-coverage-no-opportunity-for-public-input/).
[37] Cal. Ins. Code § 1861.05(a).
[38] Ibid.
[39] State Farm General Ins. Co. v. Lara (2021) 71 Cal.App.5th 148, 188.
[40] Cal. Ins. Code § 1861.10(a).
[41] Compare Donabedian v. Mercury Ins. Co. (2004) 116 Cal.App.4th 968, Fogel v. Farmers Group, Inc. (2008) 160 Cal.App.4th 1403, and Villanueva v. Fidelity National Title Co. (2021) 11 Cal.5th 104 with MacKay v. Superior Court (2010) 188 Cal.App.4th 1427, State Farm General Ins. Co. v. Lara (2021) 71 Cal.App.5th 148, and Davis v. CSAA Insurance Exchange (2025) 114 Cal.App.5th 121.
[42] State Farm General Ins. Co. v. Lara (2021) 71 Cal.App.5th 148, 188–194; Davis v. CSAA Insurance Exchange (2025) 114 Cal.App.5th 121, 133.
[43] 15 U.S.C. § 1012(a).
[44] 15 U.S.C. § 1012(b).
[45] Article p. 76; see also Federal Model Bill, Sec. 2, Purpose ¶ (5).
[46] The operative text of the Federal Model Bill, §§ 313(t)–(u), contains no savings clause. Compare 42 U.S.C. § 300gg-23(a)(1), the Affordable Care Act’s savings clause, which preserves state standards “except to the extent that such standard or requirement prevents the application of a requirement of this part.”
[47] Trump v. Slaughter (2026) 609 U.S. ___ [No. 25-332, decided June 29, 2026].
[48] The Federal Model Bill amends section 313 of subtitle I of title 31 of the United States Code—the Federal Insurance Office—by inserting new subsections (t) and (u). Coordination with state regulators is built into the text: § 313(u)(3)(B) conditions permissible dividends on a determination by “the appropriate State Insurance Regulator”; § 313(u)(3)(C) makes executive compensation “as determined by the State Insurance Regulator in accordance with guidance from the Director”; and § 313(u)(4)(C) authorizes “the applicable State Insurance Regulator or state attorney general” to enforce both new subsections. Policy Brief p. 27.
[49] The federal law that the Vanderbilt proposal would amend—31 U.S.C. § 313—provides at subdivision (k) that “nothing in the section… shall be construed to establish or provide the Office or the Department of the Treasury with general supervisory or regulatory authority over the business of insurance.” The Federal Model Bill does not amend subdivision (k).
[50] Trump v. Slaughter (2026) 609 U.S. ___ [No. 25-332, decided June 29, 2026], slip opn. at p. 2.
[51] Federal Model Bill § 313(u)(1)(A).
[52] State Model Bill § 4(b)(1)(A).
[53] Federal Model Bill § 313(u)(1)(A).
[54] State Model Bill § 4(b)(1)(A). The state provision does not extend the regulator’s power to a public insurance plan.
[55] Federal Model Bill § 313(u)(4)(A)(i)–(iv); State Model Bill § 6(a)(1)–(4). The four shared remedies are the unpaid rebate, interest, punitive damages, and the costs of the action with reasonable attorney’s fees. The State Model Bill adds “damages, remediation, restitution, or proceeds from unjust enrichment”; civil penalties of “$1,000 to $10,000 per policyholder”; and a provision that “[a]ssets of the P&C Insurer’s parent company or affiliates shall be available to satisfy any judgment.” (§ 6).